Managing personal finances becomes challenging when income barely covers everyday expenses. Housing, groceries, transportation, and utility bills often consume most of a monthly paycheck, leaving limited opportunities for savings or entertainment. The 50/30/20 budgeting rule offers a framework for organizing spending into categories. However, people with lower incomes may need to modify these percentages to reflect their financial circumstances.
Entertainment spending deserves attention when money is limited. Online activities, including games available to those who click here to explore chance-based casino entertainment, can involve financial losses. Gambling should never be treated as an income source or a budgeting strategy. Understanding discretionary spending is essential when applying the 50/30/20 method, particularly when essential costs already account for most available income.
What Is the 50/30/20 Budgeting Rule?
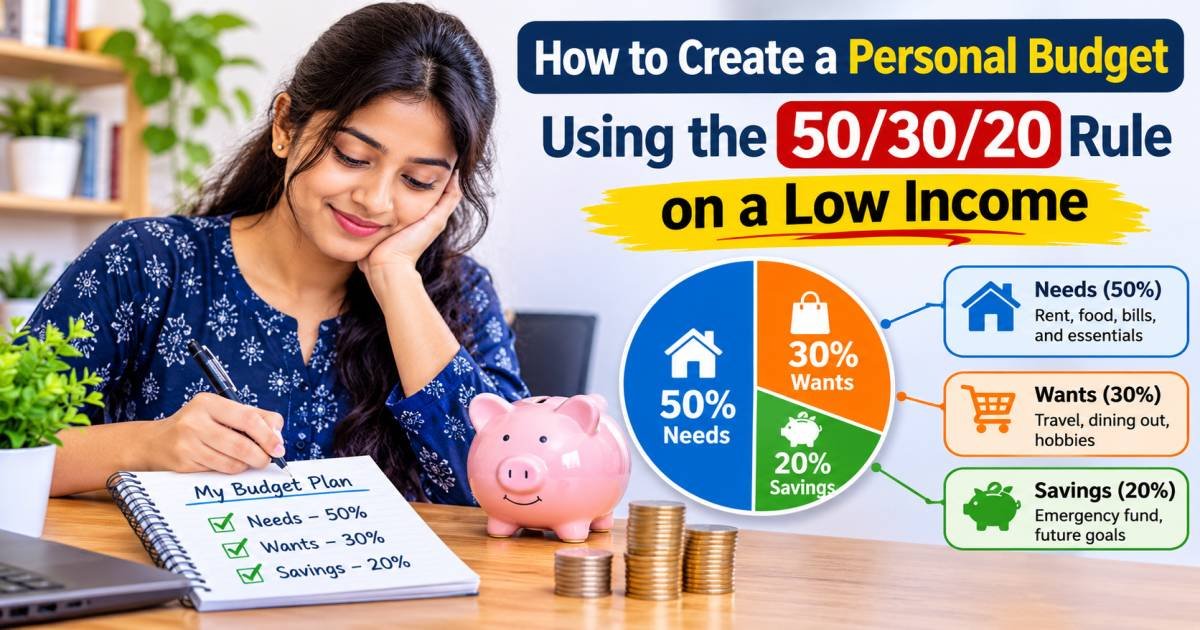
The 50/30/20 method divides after-tax income into three categories: needs, wants, and savings or debt repayment.
Under this framework, 50% of income covers essential expenses, including housing, food, utilities, and transportation.
Another 30% is allocated to discretionary spending, such as entertainment, hobbies, restaurant visits, and subscriptions.
The remaining 20% goes toward savings, emergency reserves, and payments beyond required debt minimums.
These percentages provide a starting point rather than mandatory financial rules. Their usefulness depends on income, living costs, and existing financial obligations.
Calculate Your Monthly Income
Budgeting begins with determining how much money is available after taxes and required deductions.
Employees with fixed salaries can use their monthly take-home pay.
People with variable earnings should calculate an average based on several months of income.
However, using a conservative estimate may reduce the risk of overspending during periods with lower earnings.
For example, someone receiving $1,200 per month would allocate $600 to needs, $360 to wants, and $240 to savings under the standard formula.
These amounts should then be compared with actual expenses.
Separate Needs From Wants
Distinguishing essential expenses from discretionary purchases is necessary for accurate budgeting.
Needs generally include rent, groceries, utilities, basic transportation, insurance, and minimum debt payments.
Wants include restaurant meals, entertainment subscriptions, recreational shopping, and optional services.
Some expenses can belong to either category depending on circumstances.
Internet access may be essential for someone working remotely, while an upgraded entertainment package is discretionary.
The purpose is not to eliminate enjoyable activities but to understand which expenses can be adjusted when income changes.
Why the Standard Formula May Not Work on a Low Income
The 50% allocation for necessities can be unrealistic when housing and food account for a large proportion of income.
Consider someone earning $900 monthly and paying $450 in rent.
Housing alone consumes half of their income, leaving nothing within the standard needs allocation for groceries, utilities, or transportation.
This does not necessarily indicate poor financial management.
The problem may reflect income limitations or living costs that exceed the assumptions behind the budgeting framework.
In such situations, maintaining essential expenses should take priority over meeting predetermined percentages.
Adjust the Percentages to Your Circumstances
People with limited income can use modified allocations while preserving the method’s basic structure.
A 70/20/10 budget assigns 70% to necessities, 20% to discretionary spending, and 10% to savings.
Someone earning $1,000 would therefore allocate $700, $200, and $100 respectively.
For households with greater essential expenses, an 80/15/5 arrangement may be more realistic.
The objective is to establish amounts that can be maintained consistently.
Even a small savings allocation can be useful when it does not interfere with food, housing, or necessary payments.
Build an Emergency Fund Gradually
Emergency savings provide protection against expenses that cannot be predicted precisely.
Examples include medical bills, equipment repairs, or temporary income interruptions.
People with limited income may find it difficult to save several months of expenses immediately.
A more practical approach involves establishing an initial target, such as $100 or $300, depending on financial circumstances.
Small transfers after each paycheck can support gradual progress.
Emergency savings should remain accessible and separate from money intended for everyday purchases.
The appropriate long-term target depends on household needs and income stability.
Reduce Expenses Without Eliminating Everything Enjoyable
Expense reduction works best when focused on purchases that provide limited value.
Review subscriptions, transportation costs, food waste, and recurring fees before eliminating activities that contribute to well-being.
Meal planning can reduce unnecessary grocery purchases, while comparing service providers may identify opportunities for savings.
However, people should avoid assuming every financial problem can be solved through spending cuts.
When essential expenses consume nearly all income, increasing earnings or accessing appropriate assistance may be more effective than further restrictions.
Track Spending and Review Your Budget
A budget becomes useful when actual spending is compared with planned allocations.
Record expenses through a spreadsheet, notebook, or budgeting application.
Review transactions weekly to identify categories exceeding their limits.
At the end of each month, compare planned amounts with actual results.
Unexpected expenses should prompt adjustments rather than abandonment of the entire system.
This process also helps reveal recurring costs that may have been overlooked during initial planning.
Manage Debt Within the Budget
Debt obligations require additional consideration when establishing spending priorities.
Minimum required payments belong among essential expenses because missing them can result in fees or other consequences.
Additional payments toward debt principal can be included in the savings and repayment category.
High-interest debt may deserve priority over certain discretionary purchases or long-term savings goals.
However, maintaining a small emergency reserve can reduce the need for borrowing when unexpected expenses occur.
A realistic repayment plan should reflect interest rates, payment requirements, and available income.
Make the Budget Sustainable Over Time
The 50/30/20 rule provides a framework for financial planning, but its percentages should reflect actual circumstances.
People with lower incomes may need to allocate more money toward necessities while maintaining smaller savings targets.
Regular expense tracking, realistic spending limits, and gradual financial adjustments can help improve stability.
The purpose of budgeting is not to follow a formula perfectly. It is to understand where money goes, protect essential needs, and make deliberate decisions that support financial security over time.
Read more articles from ShayariShort